Budgeting Skills for Adults: Track, Plan, and Save
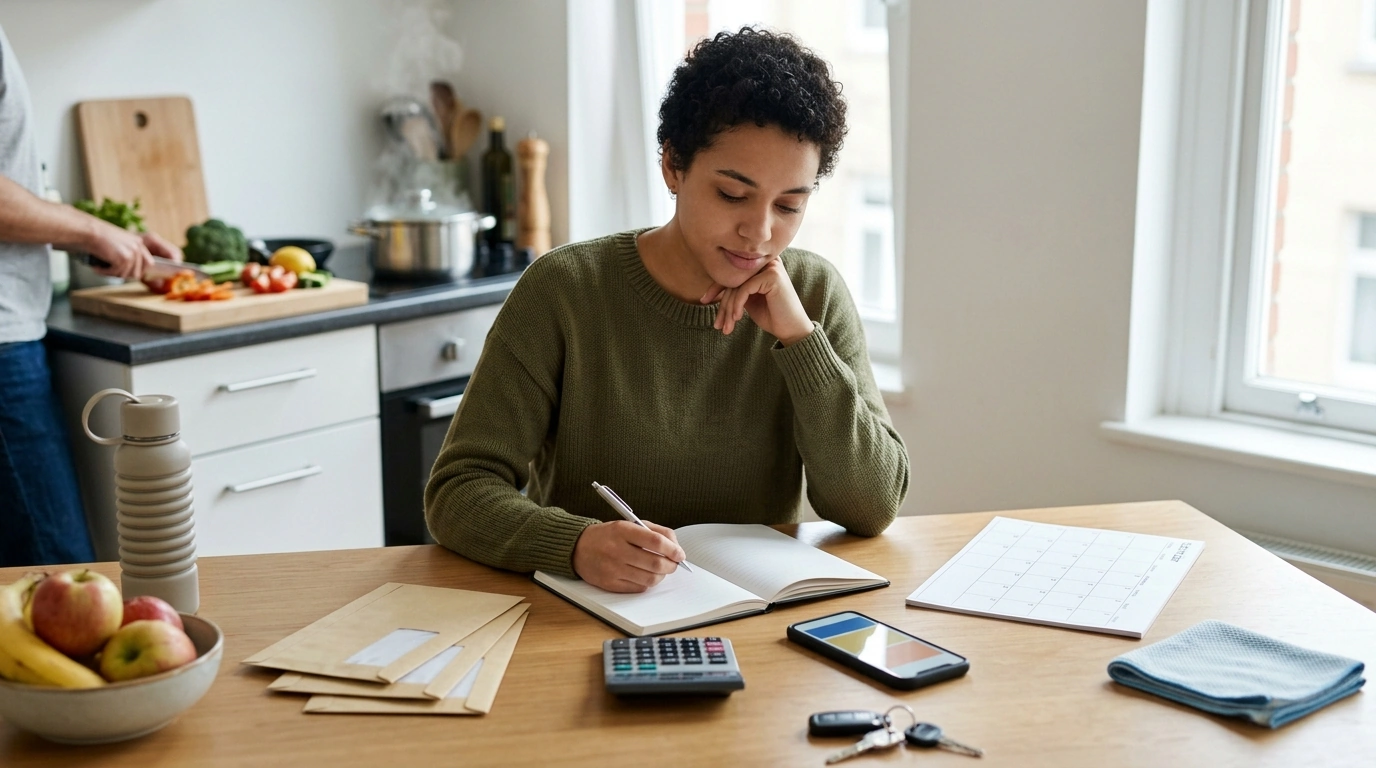
What are some effective budgeting skills for adults?
Effective budgeting skills help you control cash flow, avoid surprise expenses, and make steady progress toward goals. The best systems are simple enough to use every week and specific enough to guide everyday decisions.
Track spending with a “money snapshot”
Start by listing your monthly take-home income and your fixed bills (rent/mortgage, utilities, insurance, minimum debt payments). Then review the last 30 days of transactions and group them into a few categories (groceries, dining, transportation, subscriptions, personal). This snapshot makes it easier to spot patterns—like multiple small charges that add up.
Use a realistic plan, not a perfect one
Pick a framework you’ll actually follow: a 50/30/20 split, a zero-based budget, or a simple category budget. The key skill is assigning every dollar a job (bills, savings, debt, spending) so you’re deciding ahead of time rather than reacting later.
Automate essentials and build an emergency buffer
Set up automatic transfers to savings right after payday, even if it’s small. Aim for an initial $500–$1,000 buffer, then grow toward 3–6 months of essential expenses. A buffer turns unexpected costs into inconveniences instead of crises.
Plan for irregular expenses
Adults get hit with non-monthly costs: car repairs, gifts, annual renewals, medical co-pays. Create “sinking funds” by setting aside a little each month into specific buckets so these expenses don’t derail your budget.
Review weekly and adjust quickly
A 10-minute weekly check-in helps you catch overspending early, cancel unused subscriptions, and move money between categories before it becomes a problem. Budgeting is a living plan—adjustments are a skill, not a failure.
For more practical adult life-management tips that pair well with budgeting, visit the full guide here: https://reliableitemsstash.shop/guide-adult-skills-budgeting-communication-media-literacy-life-management/.
FAQ
How can I budget when my income changes every month?
Base your plan on a conservative “low month” income and prioritize essentials first. In higher-income months, top up sinking funds, build your emergency fund, and pay extra toward high-interest debt.

Leave a comment